Casinos That Accept Wire Transfers in the UK
 Available in GB
Casino cashiers may use “bank transfer” for a specific payment route, so availability and process can vary between methods.
Table of Contents
- How bank transfers fit into a UK casino cashier
- Check availability and currency before you deposit
- Match the casino account to the bank account
- What can affect a casino wire transfer
- Deposit amounts and payment limits
- How long a bank-transfer deposit may take
- Bank-transfer withdrawals and casino checks
- Compare the full cost, not just the visible fee
- How casino winnings are returned by bank transfer
- The charges that can apply to a wire-transfer payment
How bank transfers fit into a UK casino cashier
A bank transfer is one way to move money between your bank account and a casino account. It can be useful if you prefer to pay from your bank rather than use a card or an e-wallet, but the label does not describe a single, identical process at every cashier. A conventional bank transfer and a payment made through open banking both involve your bank, yet the route and the experience can differ. You should treat the cashier’s wording as important: “bank transfer” may refer to a particular payment route rather than every kind of transfer your bank can make.
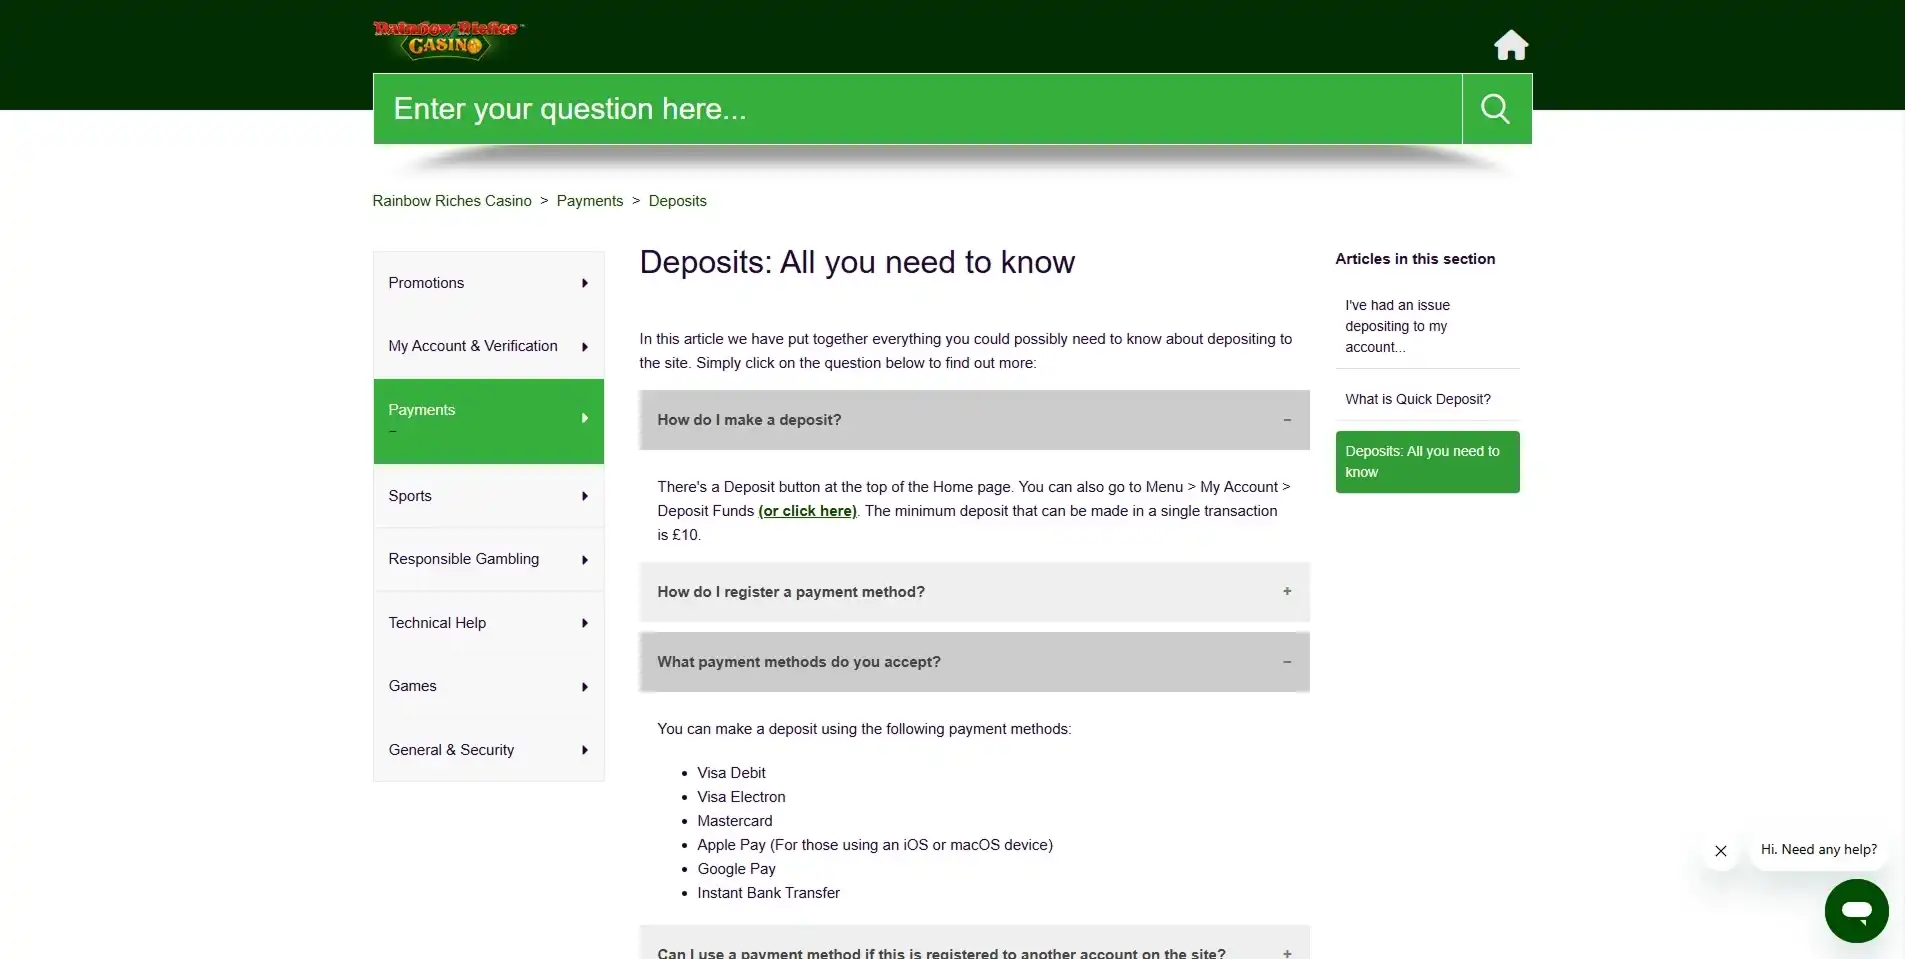
The wider cashier may also show card payments and digital payment services. Debit cards, including Visa and Mastercard, are commonly accepted by UK casinos, while PayPal, Skrill and Neteller are among the e-wallet names you may encounter. Apple Pay is accepted for deposits at some UKGC-licensed casinos. Paysafecard is a prepaid voucher for deposits only, so it should not be read as a general-purpose route for moving money both ways. These options are not interchangeable: each has its own role, and a method that appears in a cashier is not automatically available for both deposits and withdrawals.
When looking for a UK casino that accepts wire transfer, payout timing is one practical detail to check. Use these verdicts as a quick reference to the payout-speed information available.
Payout speed: 1-3 business days EvoSpin has a stated payout speed of 1–3 business days. Check the casino’s terms to see how this applies to wire transfers.
Payout speed: 1-3 business days Amunbet has a stated payout speed of 1–3 business days. Check the casino’s terms to see how this applies to wire transfers.
Payout speed: 1-3 business days Jetsetspins has a stated payout speed of 1–3 business days. Check the casino’s terms to see how this applies to wire transfers.
Payout speed: 1-3 business days Britsino has a stated payout speed of 1–3 business days. Check the casino’s terms to see how this applies to wire transfers.
Payout speed: 1-3 business days NightWin has a stated payout speed of 1–3 business days. Check the casino’s terms to see how this applies to wire transfers.
Payout speed: 1-3 business days WinBeast has a stated payout speed of 1–3 business days. Check the casino’s terms to see how this applies to wire transfers.
Payout speed: 1-3 business days BeOnBet has a stated payout speed of 1–3 business days. Check the casino’s terms to see how this applies to wire transfers.
Payout speed: 1-3 business days SlotoSport has a stated payout speed of 1–3 business days. Check the casino’s terms to see how this applies to wire transfers.
Payout speed: 1-3 business days SpinFormula has a stated payout speed of 1–3 business days. Check the casino’s terms to see how this applies to wire transfers.
Payout speed: 1-3 business days x3bet has a stated payout speed of 1–3 business days. Check the casino’s terms to see how this applies to wire transfers.
Credit cards are different. UK-licensed casinos cannot accept credit-card payments for gambling, and the restriction also covers credit-card funds routed through a money service business. A wallet cannot be used where it permits credit-card funds to be used for gambling. That means a payment option should be judged by how it is funded as well as by its name. A debit card is not the same as a credit card, and the payment route must comply with the rules that apply to the casino.
Banking-based payments can sit between familiar card payments and e-wallets in the way they connect to your finances. In some arrangements, you authorise a payment through your bank; in others, you may be asked to send a transfer using bank details or an instruction supplied by the casino. The word “bank” alone does not tell you whether the cashier uses open banking, a conventional transfer, or another service. Nor does it establish that the same route will be offered for paying in and cashing out.
A specialist review reports that open banking and bank transfers can support instant deposits and fast withdrawals at many sites. That is a description of possible performance, not a promise about every UK casino or every transfer. “Bank transfer” can cover routes with different handling, and the cashier’s method name may not reveal the full process. A fast bank-based payment at one operator does not prove that another operator uses the same system or offers the same speed.
This distinction matters when you compare payment choices. An instant deposit means the casino receives or recognises the payment promptly enough for the balance to be credited; it does not establish that all transfers are instant. A withdrawal is a separate movement of money back to you, and a casino may handle it differently from a deposit. Open banking is not simply another name for every bank transfer, while a traditional transfer should not be assumed to behave like an instant payment service.
The cashier is therefore the practical starting point for understanding what a particular casino supports. Look at the payment method’s exact label and whether the screen presents it for deposits, withdrawals, or both. Do not infer that a bank-transfer logo or a bank-related option guarantees a particular route in both directions. The important point at this stage is to distinguish the broad family of bank-based payments from the specific option the casino actually presents.
The same care applies when comparing bank transfers with other methods. Debit cards are familiar to many customers; e-wallets provide a separate account-based route; prepaid vouchers are designed for deposits rather than withdrawals. Some payment services may also have promotion conditions. A specialist source has reported that PayPal may be excluded from bonus eligibility, while another specialist source has described Skrill and Neteller as sometimes excluded from promotions. Those terms can change, so the cashier and the casino’s current promotion rules matter more than a general assumption about a payment brand.
A bank transfer can make sense if you want a payment route connected to your bank and the casino offers one that suits your needs. It is not inherently faster, slower, or more suitable than every alternative: the method label alone cannot settle that. Treat open banking and bank transfers as related but distinct possibilities, then assess the actual option displayed by the casino rather than assuming all bank-based payments work alike.
Do
- Check the exact label of the payment method
- Verify if the method is available for both deposits and withdrawals
- Treat open banking and conventional transfers as distinct options
Don’t
- Assume a bank-transfer logo guarantees a specific route
- Infer that a method available for deposits is automatically available for withdrawals
- Assume all bank-based payments work identically across different operators
Check availability and currency before you deposit
A casino’s payment page can mention bank transfers without confirming that a bank-transfer route is available to every customer. Payment options may depend on the account, the cashier’s current setup and the route offered at the point of payment. If you are looking for an online casino that accepts wire-transfer deposits, treat a general payment-method list as a starting point, not proof that you can use that method for your own deposit.
Sign in and open the cashier before moving money. Check the deposit options shown for your account, and look for the exact wording of the bank method. “Bank transfer”, “bank wire” and an open-banking option may describe different ways to authorise a payment; they should not be treated as interchangeable simply because each involves a bank. Read the instructions attached to the option, including whether they describe a transfer from your bank or a service that connects to it. If the method is unclear, ask the casino’s support team to confirm what the cashier means before proceeding.
The distinction matters when comparing online casino sites that accept bank wire transfers. A site may support one bank-payment route while not offering another. A page that says “bank transfer” may not establish that the casino accepts a manually arranged wire, or that the route is currently available in the UK. Check the cashier itself for your account rather than relying only on an older review, a general list of payment methods or a search result. Payment arrangements can change, and a site-wide description may not show the options available to you.
A specialist review can be useful as an initial reference, but it cannot settle whether a method appears in your cashier now. The same caution applies to card information: a specialist review may list Visa or Mastercard, but current UK availability and eligibility depend on the cashier and the specific card product. If a card option is visible, check its terms there rather than assuming every card carrying that brand will work. The brand name alone does not confirm that a particular product is eligible.
Confirm the account currency
Check the currency shown in your casino account before making a first transaction. Specialist pages may state that GBP is supported, but that does not confirm which currency has been selected for your own account. If your account is set to another currency, a payment in pounds may be converted; if you want to avoid that conversion, confirm that the account is set to GBP before you deposit.
Look for the currency in the account settings or cashier and read any confirmation screen carefully. Do not assume that choosing a UK-facing site automatically sets the account to pounds. Nor should you infer the casino’s account currency from the currency displayed by your bank. The two can differ. If the cashier does not make the account currency clear, ask support to confirm it and whether changing it is possible before you proceed.
Deposit Availability Checks
- Sign in and open the casino cashier
- Check the exact wording of the bank method available for your account
- Read the instructions for the selected payment route
- Confirm that the account currency is set to GBP
- Verify the method is explicitly offered at the point of use
Currency is a compatibility check, not just a display preference. The currency used by the casino can affect how the payment is handled, while the bank’s own account and payment route have their own settings. Establishing the casino account currency first gives you a clearer basis for deciding whether the proposed transfer is suitable. It also helps prevent a confusing situation in which the deposit appears in a different currency from the one you expected.
Check the payment option at the point of use
Before confirming a deposit, make sure the selected method is explicitly offered in the cashier and that its instructions match what you intend to do. Check whether the screen identifies a bank transfer, a bank wire or a connected banking service, and note any conditions or exclusions attached to that route. If the option is absent, do not assume that a support page or an old payment list means you can still use it. Ask the casino whether it is available for your account.
For anyone comparing the best wire-transfer online casino options, “best” should not be decided from a method name alone. First establish that the casino actually offers the relevant route, that it is available to you in the UK, and that your account currency is suitable. A bank-payment option that cannot be selected in your cashier is not a usable option, however prominently it appears elsewhere.
Do these checks before entering payment details or authorising a transaction. Confirm the route, confirm the account currency, and make sure the instructions are for the payment method you mean to use. If any of those points remain ambiguous, pause and get a clear answer from the casino rather than testing the assumption with a deposit.
Match the casino account to the bank account
When you fund a casino account by bank transfer, the details on both sides should point to the same customer. Using your own bank account and your own casino account makes the basic ownership picture easier to follow. A mismatch can create avoidable questions before a transaction is accepted or processed.
That does not mean every difference will cause a problem, or that matching details guarantee a smooth transaction. A casino may still need to check your account. The practical point is narrower: when the name and payment route belong to you, there is less uncertainty about who is moving the money.
Keep the account ownership clear
Use a bank account held in your name rather than someone else’s. If a partner, relative or friend sends money from their account, the transfer may not look like a payment from the casino customer. Even where the other person has given permission, that does not make the account theirs. The casino may need to clarify the connection, and the transaction can face extra friction.
The same principle applies when you enter payment details. Take care that the information identifies the account you actually use. A small inconsistency may be innocent, but it can make it harder to establish that the bank account and casino account belong to the same person. If you notice an error, correct it through the casino’s proper account or support process rather than trying to work around it with another person’s payment route.
A shared or jointly held account may also leave questions about ownership if the casino cannot readily connect it to the named customer. Check the operator’s instructions before using one. Do not assume that access to an account is the same as being its sole or named holder.
Account Ownership
Using a bank account held in another person’s name, such as a partner or friend, can create friction and may require the casino to clarify the connection before the transaction is accepted.
Be consistent about the payment route
The cleanest arrangement is often one named account used consistently for deposits and withdrawals. Keeping to that route can make the transaction history easier to understand than switching between accounts belonging to different people or changing payment details without a clear reason.
This is a practical preference, not a promise that every casino will handle every transfer identically. Payment arrangements and account checks are set by the operator, so follow the instructions shown in your cashier and account. If the casino asks you to confirm ownership, respond through its stated channel and provide only information requested for that check.
Consistency can matter even if you have more than one bank account of your own. Before using a different account, consider whether the casino can identify it as yours and whether the payment route is permitted under its terms. If anything is unclear, ask the operator before sending money; resolving a question in advance is less disruptive than discovering it during a transaction.
A match does not replace verification
Matching the bank account to your casino account is not a way to avoid KYC, or the operator’s identity and account checks. Remote gambling licensees may still need to verify information, and a first transaction does not establish that all checks are complete. Keep your account details accurate and respond promptly if the casino requests clarification.
Nor should a payment from a matching account be treated as proof that a transaction will be approved automatically. It simply reduces one avoidable source of uncertainty: whether the person named on the casino account is also the person associated with the bank account and payment route.
For a casino that accepts bank wire transfer, the useful habit is straightforward: use an account in your own name, enter details carefully and keep to a consistent route where possible. If you need to change accounts, check the operator’s requirements first. That will not remove every possible check, but it can prevent a basic ownership mismatch from complicating an otherwise clear payment.
What can affect a casino wire transfer
A bank transfer can be delayed by the point at which you send it, the days on which banks process it and whether the payment needs currency conversion. These are delivery factors: they concern the movement of money between accounts, not the casino’s separate decision to approve a transaction.
A specialist review identifies cut-off times, weekends and currency conversion as variables that can affect bank-transfer delivery. The practical effect is that the time you initiate a payment may not be the time the receiving account is credited. A transfer sent close to a bank’s processing cut-off may not enter the next stage straight away. The relevant cut-off is set by the bank or payment route involved, so a casino’s general description of its cashier cannot tell you exactly when your own transfer will be handled.
Weekends can matter for the same reason. If a transfer is initiated when the relevant banking process is not operating, its movement may be affected until processing resumes. That does not mean every bank treats weekends identically, or that every transfer will be held for the same period. Check the sending bank’s information for the route you are using, and distinguish its processing guidance from any estimate shown by the casino.
Bank transfer delivery can be affected by processing cut-off times, weekends, and whether the payment requires currency conversion.
Currency conversion is another possible influence. If the money is converted during the transfer, that can affect delivery as well as the amount credited. The sequence may involve more than simply moving funds between accounts in the same currency, so avoid assuming that the timing for a domestic, same-currency payment applies. The account currency and conversion arrangements are worth confirming before you initiate the payment; the relevant details may depend on the bank and the route.
These factors can combine. A transfer sent near a cut-off, around a weekend, or through a route involving conversion may not follow the same path as a payment sent at another time in the same currency. That is a reason to treat a displayed estimate as guidance rather than a guaranteed arrival time. Keep the transfer confirmation and reference details, since they can help the bank or casino trace a payment if it has not appeared.
It is also useful to separate transfer delivery from casino processing. A bank can deliver funds to an account, but the casino may still need to record or review the transaction before it appears in your balance. Conversely, a casino’s stated processing status does not by itself show where a bank transfer is in the banking system. If a payment is delayed, check whether it has left the sending account and ask the bank about the transfer route before assuming the casino is holding it.
For a wire transfer to a casino, the key practical checks are therefore the sending bank’s cut-off information, whether the transfer crosses a weekend, and whether conversion is involved. None of those variables provides a precise arrival time on its own. They explain why two payments made through the same casino cashier can be delivered differently, without implying that the casino has approved or rejected either one.
Deposit amounts and payment limits
The amount needed to open a casino balance is not necessarily the same for every payment method. A specialist casino review puts the starting minimum in the £10–£20 range, with the precise threshold depending on the method selected. Treat that as a guide rather than a promise: the cashier’s displayed minimum is the amount that applies to your account and chosen route.
For a wire transfer, check the minimum shown beside that option before entering payment details. A casino may set a different floor for bank transfers than for cards or other methods, and the amount can be affected by the account’s settings. If the cashier shows a minimum higher than the amount you intended to deposit, do not assume that splitting the payment will work; each transaction may be subject to its own rules.
The maximum is a separate question. A specialist review notes that deposit ceilings can apply per transaction, per day or per month, and that they vary with the payment method and the account’s status. In practice, this means a transfer that is within the single-payment cap could still be affected by a daily or monthly ceiling. The cashier or the operator’s payment terms should identify which limit is relevant; if they do not, ask customer support before sending money.
Account status matters because operators may apply different limits to different customers or accounts. Do not infer your permitted amount from a general payment-method description, another player’s experience or a limit shown before signing in. Check the figures available in your own account, and confirm any uncertainty with the operator. A payment that exceeds a limit may not be handled as you expect, so it is better to establish the applicable cap before initiating a bank transfer.
Understanding Payment Limits
A casino may set a different minimum for bank transfers compared to cards. Maximum limits can be applied per transaction, per day, or per month, and these may vary based on your account status.
Casino deposit ceilings are also distinct from personal spending controls. UKGC rules require remote gambling operators to ask new customers to set a financial limit before their first deposit and to make account-level limit controls accessible. This is a tool for deciding how much you are willing to spend, not a statement of the maximum a payment method will accept. Your own limit may therefore be lower than the cashier’s permitted maximum.
When planning a deposit, check both figures: the payment method’s minimum and maximum, and the financial limit set on your account. A low minimum does not mean a high maximum is available, while a generous payment ceiling does not mean you should use it. Choose an amount you can afford to lose, and use the account controls if you want to restrict future deposits.
How long a bank-transfer deposit may take
There is no single arrival time that applies to every bank-transfer deposit. If you are asking how long a casino wire transfer takes, the answer depends in part on when the payment is sent, whether it crosses a weekend and whether currency conversion is involved. A specialist casino payment review identifies these as factors that can affect delivery, rather than giving one timetable that fits every transfer.
The time you make the payment can matter because a bank may have a cut-off for processing transfers. A payment sent after that point may not enter the relevant processing flow straight away. The cashier’s displayed status may therefore differ from what you see in your bank account: an instruction can be submitted without the funds having reached the casino.
Weekends can also affect the wait. If a transfer is initiated near the end of the working week, the calendar time before it arrives may be longer than for a payment sent earlier. That does not mean every transfer pauses for the entire weekend; it means you should not assume that elapsed hours translate directly into processing progress.
Currency conversion adds another possible variable. When the payment and the casino account use different currencies, conversion may be part of the route. That can affect when the casino receives and recognises the funds, as well as the amount credited. The account currency is worth checking before you send money, but the timing point is simple: a transfer involving conversion may not follow the same path as one that does not.
If a deposit has not appeared, check the transfer status with your bank and the payment status in the casino cashier. Compare the details shown in both places, including whether the payment is still being processed or is marked as completed. If the bank shows completion but the casino balance has not changed, contact the casino’s payment support with the transaction reference. If the bank has not completed the instruction, ask the bank what stage it has reached.
A delay in deposit delivery is separate from a casino’s approval of a withdrawal. A deposit is still travelling to the casino; a withdrawal involves the casino processing a request before funds are sent out. Keeping those stages distinct makes it easier to identify which organisation to contact when a payment seems stuck.
Resolving Deposit Delays
Verify if the transfer has left your sending account and check the route status.
Compare the payment status in the cashier to see if it is marked as processing or completed.
If the bank shows completion but the balance has not changed, provide the transaction reference to the casino’s payment support.
Bank-transfer withdrawals and casino checks
A bank-transfer payout is not necessarily sent wherever you choose. UK anti-money-laundering rules commonly require a casino to return funds to the original payment source. This is part of a control intended to keep money moving through a traceable route, rather than a guarantee that every withdrawal will follow the same process.
Before release, the casino may need to approve the withdrawal and confirm that your account is fully verified. These are separate steps from the bank’s handling of the transfer: a payout can be waiting for the casino’s review before it has been sent at all. A specialist review notes that withdrawal times can depend on both internal approval and verification status; the operator’s own cashier or terms are the place to check its current procedure.
The first withdrawal can take longer if the casino still needs documents or other information to complete checks. That does not necessarily mean there is a problem with the transfer. It may mean the operator has not yet finished reviewing the account or the request. Responding promptly to a request can avoid adding further delay, but it cannot determine how quickly the casino will complete its review.
If the casino cannot return the money through the original source, it may ask for another route or further evidence before paying. Do not assume that selecting a different bank account will make the process quicker: an alternative can prompt additional verification, and the casino must still follow its payment controls.
For an online casino bank-transfer withdrawal, check the cashier’s stated steps and any messages in your account. If the status remains unclear, ask whether the request is awaiting approval, verification or dispatch. That distinction helps you identify whether the next action belongs to you, the casino or the bank. A transfer that has not been approved is not yet in the bank’s processing queue.
Compare the full cost, not just the visible fee
A bank transfer can look inexpensive when the cashier shows no charge, but that figure may not represent the full cost of moving money. A specialist review’s comparison of payment methods cautions against treating any one option as the cheapest in every case: the result depends on the amount and the charges attached to the route.
Compare the same planned transaction across the costs that could apply. These may include a charge from the casino, a payment-provider fee, a fee from your bank or another issuer, a network charge, and any cost built into currency conversion. Not every payment will involve every item, and a cost may be shown separately or reflected in the amount that reaches the account.
The exchange rate deserves particular attention. A conversion spread is the difference between the rate applied to your transaction and a reference rate; it can cost more than a visible flat fee. So a transfer with no prominent charge is not automatically cheaper than one with a stated fee. Look at the amount you would pay in total and the amount that would be credited, using the same transaction value for each comparison.
Check the casino’s payment information alongside the terms of your bank and any provider involved. A casino’s cashier may show its own charge without accounting for what your bank might apply, while a provider’s displayed fee may not include conversion costs. If the payment is in a different currency from the one used for your account, include the conversion effect in the comparison rather than judging by the headline fee alone.
Hidden Costs
Do not assume a transfer is free just because the casino shows no charge; currency conversion spreads and bank fees can often cost more than a visible flat fee.
There is no reliable universal winner. The lowest-cost route for one amount may not be the lowest-cost route for another, because a flat fee and a conversion spread affect the total differently. Compare the full cost for the transfer you intend to make, not a general claim that a particular method is free or cheap.
How casino winnings are returned by bank transfer
A casino may send a withdrawal by bank transfer, but the route is often linked to how you funded the account. Returning money to the original payment source is a common anti-fraud and anti-money-laundering control. In practice, if you deposited by bank transfer, the casino may direct the payout back through that route rather than let you nominate an unrelated account.
This is part of what is often called a closed-loop approach: money goes back to the source used to pay in. It helps the operator check that funds are being returned to the customer who supplied them, rather than diverted to another person or account. The exact options depend on the casino’s cashier and its rules, so a bank-transfer deposit does not, by itself, guarantee that every withdrawal will be paid by bank transfer.
If you ask for winnings to go to a different bank account or another payment method, the operator may ask for additional verification before processing the request. That can mean showing that the alternative route belongs to you or explaining why the original source cannot be used. Keep the account details and payment records available in case the casino needs to establish the link.
Before depositing, check how the operator describes withdrawals for the method you intend to use. Look for whether bank transfer is listed for withdrawals as well as deposits, and whether payments are returned to the original source. A method shown only for paying in should not be assumed to support cash-outs.
The practical point is simple: plan around the return route, not just the deposit button. If you need winnings sent to a particular account, confirm that the casino permits that route and be prepared for extra checks if it differs from the source of your funds.
The charges that can apply to a wire-transfer payment
A wire transfer to a casino can carry costs at more than one point in the payment chain. A specialist payment review identifies possible charges from the casino, the payment provider, your bank or card issuer, currency conversion and the network used to move the funds. Which of these applies depends on the route and the terms shown by each provider; a transfer should not be assumed to be free simply because the casino does not display a fee.
Start with the casino’s cashier. It may state whether it charges for a deposit or withdrawal, but that is only one part of the cost. A bank or intermediary may charge separately, and a payment provider can have its own fees. Check the terms for the specific transfer route rather than relying on a general statement about bank transfers.
Currency conversion can be less visible. If the casino account and the sending account use different currencies, the conversion rate may include a spread: the difference between the rate applied and a reference market rate. A specialist payment review notes that this spread can cost more than a stated flat fee. The amount may be built into the exchange rate rather than shown as a separate line, so look for the rate you will receive as well as any listed charge.
Network costs may also apply when a transfer passes through intermediary institutions. These can be deducted along the way or appear as a separate charge, depending on the route. That means the amount leaving your bank and the amount credited to the casino account may differ.
Before confirming a wire transfer payment to a casino, review the cashier’s fee information and your bank’s tariff, then check the provider’s terms and the conversion rate. Keep the confirmation details so you can compare the amount sent with the amount received. The final cost is the combination of charges and any exchange-rate difference, not just the most prominent fee.
What is the fastest withdrawal method for UK casinos?
PayPal, open banking services and debit cards connected to fast payout systems are generally among the quickest options. The casino’s approval process and whether your account is verified also affect how quickly you receive the money.
Do UK casino withdrawals require verification?
Yes, verification may be needed, particularly for a first withdrawal. Completing verification can help avoid delays while the casino approves your payout.
Why can a fast payout casino still delay my withdrawal?
A casino’s internal approval process and incomplete account verification can slow a withdrawal, even when the payment method is usually fast. Bank transfers may also be affected by cut-off times, weekends and currency conversion.
Is Skrill available?
Yes, Skrill is available at some UK-friendly casino sites and remains a common deposit option. Check the cashier and promotion terms, as Skrill may be excluded from bonuses.
What is the current minimum deposit?
The minimum deposit usually starts at £10–£20, depending on the payment method.
Are Visa and Mastercard deposits definitely debit cards?
No, the card names alone do not confirm which card products are eligible. UK casinos commonly accept debit cards, but check the cashier; credit cards cannot be used for gambling at UK-licensed casinos.
Which method has the lowest fees?
There is no universally cheapest method. Compare the casino’s charges, provider and bank fees, currency-conversion spread and any network costs for your transaction.
Prepared by the Rainbow Riches Casino 5 editorial staff.